Features
Stealing from my Momo wallet

I have always prided myself as a smart Alec. I have tried to be ahead of evildoers, scammers and other fraudsters. As a result, I have never used an ATM card for bank transactions. Not that I ever had so much to be afraid of losing. There is an Ewe proverb which translates to mean that even if you don’t have anything of value, you still have to lock your door.
I got my first MTN Sim Card in 2002 after having used a tiGO one when that company started as Mobitel. The number began with 0244 because that was what the NCA had granted the company at the time it began operations. I still have that number which I registered a money transfer regime with, after pressure from people who would want to transact money transfer business with me.
Then about six years ago, I visited a cousin who was a Medical Officer in Cape Coast to spend a couple of days. On the morning of the second day an SMS pop-up showed on the screen of my phone from a strange number purporting to have credited my MoMo account with over a thousand cedis. What intrigued me was that the balance as indicated from this “transfer” actually showed that if I subtracted the purported addition I would still be left with the amount already in the account.
Suddenly a call came through from someone claiming to have inadvertently credited my account with a thousand that was meant for someone else and that I should go through a certain process to revert the money to him. He claimed he was calling from Winneba. I told him that because it came from a certain number I was only going to resend his text to him so he could have his money. I did not understand the method he wanted to show me and I told him I was not conversant with what he wanted me to do. I told him I was going to Pedu to get it transferred back to him and he agreed.
I quickly drove to Pedu, told a vendor that cash was accidentally dropped into my account and that he should reverse the transaction for me. He took my word and started the process, then realised that the amount in my wallet was not up to a thousand so he could not continue. I did not understand until he scrutinised what was on my phone. “Money transfers don’t come as text message from numbers, Sir. They come with Mobile Money,” he quipped and said it was a scam. The bloke at Winneba called to check if I had done the transfer. Before I could say he was a fool, he hung up.
Before the end of that day I had eight calls from people claiming to be at Kasoa and had moved various sums into my MoMo wallet and asking me to check my account balance in case there was no notification on the screen of my phone. I wondered why my number was a target. How did they get my phone number in the first place? When I tried to find out, I was told these scammers dial numbers randomly, but it turned out that their main targets were numbers beginning with 0244 because that was the initial prefix from MTN so the users were likely to be the elderly who were not technology savvy to suspect they could be victims of a scam.
Their modus operandi has changed over the years. The moment a substantial amount of money hits my phone, a message would pop up asking me to enter my PIN code to complete a “Cash Out” transaction. The latest was just a couple of days ago and the destination was to GCB Bank. I called a friend at one of the branches of the bank just to ask a few questions. The bank was likely to be a victim as well.
I have spoken to the numerous friends who work at MTN. Their response was that under no circumstance should I ever enter my PIN code if I did not authorise any transaction because the fraudsters cannot do that on my behalf. But these scammers never let up. They would call and if they realised that you detected they were fraudsters, another person would call, claiming to be a staff of MTN, to inform you that the previous caller was a fraudster and that you must follow certain steps to protect your account being scammed. In my case, this particular scenario only plays out when I am driving. And it has happened more than 20 times in just a couple of months.
Only last week, I chanced upon a young man who is a mobile money vendor. I poured out my encounters with these scammers and wondered how they could detect a cash lodgement into my account because the latest one requested my PIN code for the transfer of an odd 1,472 cedis. How did the scammer ask for the transfer of that amount? The young man told me these fraudsters have accomplices in the Telcos, in my case, the MTN. The accomplices follow all transactions of clients and relay the information to the scammers and when people fall victim, the proceeds are shared among them.
According to this guy, the scammers are mostly semi-literate or school dropouts who do not have the technological capacity to run the system of the Telcos to follow people’s financial transactions, unless there is someone from the inside. I believed him because the English these scammers speak makes me wonder if the Telcos conduct proper interviews if these blokes were really their staff. Videos abound on social media on the activities of these fraudsters, yet their activities continue unabated.
I am on tiGO-Cash and V-Cash as well, but I have had not a single issue with scammers on their platforms. It’s only MTN. They might be the market leader so they easily attract the hoodlums, but do they have any system in place to monitor the conversations between their staff in the sensitive money area with their clients or partners in crime? If, indeed, there are moles in the Telcos there must be a way to flush them out.
The mobile money is great service for the ordinary folks like me and my relatives in the countryside and everything must be done to protect us from societal deviants and criminals.
If the activities of these criminals were not lucrative they would have folded up by now. Customers need to be protected because not all of us understand what these transactions on these devices entail. The regulators must find a way to ensure that clients of these mobile money regimes are protected. They should not only concern themselves with revenue they get from the operators. They should not allow stealing from our MoMo wallet.
Writer’s e-mail address:
akofa45@yahoo.com
By Dr. Akofa Segbefia

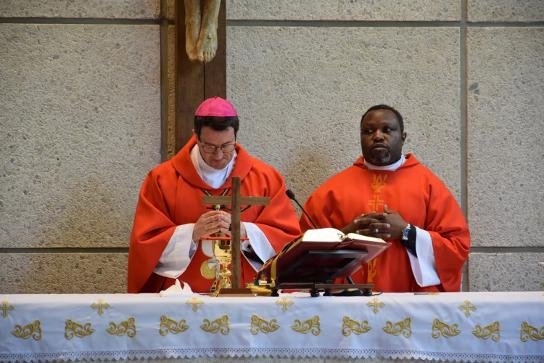
On Sunday, October 11, 2026, it was the turn of Ghanaian Catholics in Finland to lead the singing in the church service of the African Catholic Chaplaincy in Finland (ACCF).
It was indeed a spirit-filled feeling for worshippers present. And for the Ghanaian migrants, the occasion also brought back to them memories of church services in their home country, Ghana.
The ACCF has a roster for each country/community to sing from time to time. Next Sunday will be the turn of the Nigerian community. Other communities that usually sing are the Kenyan/Tanzanian community, the Cameroonian, the Ugandan, group, etc.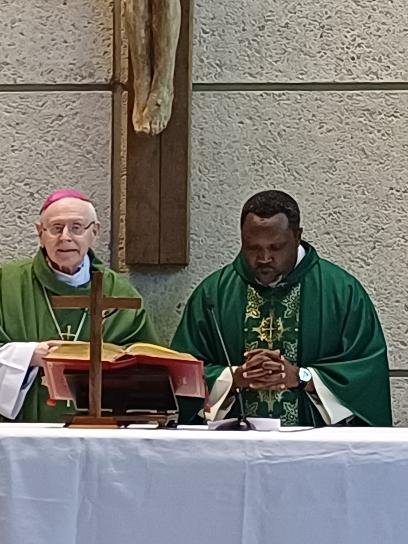
A powerful religious experience
The mass services of the Chaplaincy usually give a powerful religious experience and a display of cultural diversity, especially in occasions such as when the Bishop of Helsinki, Bishop Raimo Goyarrola, celebrated mass with the Chaplaincy on Pentecost Day, May 24, 2026.
There was a similar time of spiritual joy last month (September 27, 2026) when Emeritus Bishop Teemu Sippo, former Bishop of Helsinki, visited the Chaplaincy. Bishop Teemu was the main celebrant, assisted by the Chaplain, Reverend Father Thomas Otieno.
Last Sunday, Reverend Father Bernard Sor, a Ghanaian Catholic priest based in Austria, was the main celebrant in the mass service where he performed a rite of baptism. Fr Bernard had celebrated mass a few months ago when he visited his sister and her husband in Helsinki. 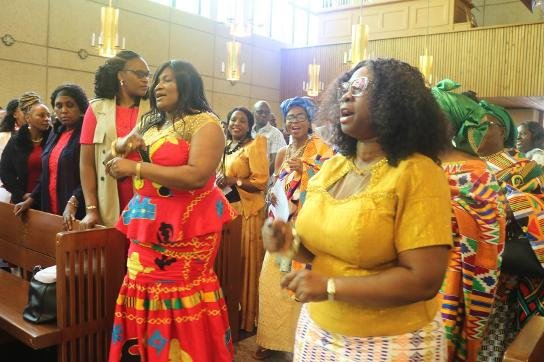
All these well-attended religious occasions indeed leave lasting memories. The homilies (peaching) by the priests usually emphasize religious tenets such as the importance of loving and serving God in truth, existing in peace with our fellow humans to promote unity in diversity, etc.
Unity in diversity and a colourful display of cultures
The African Chaplaincy church services usually produce impressive displays of diverse cultures from different parts of Africa and elsewhere. The events are often spiced by rich cultural displays of dances and colourful attires which are a delight to watch.
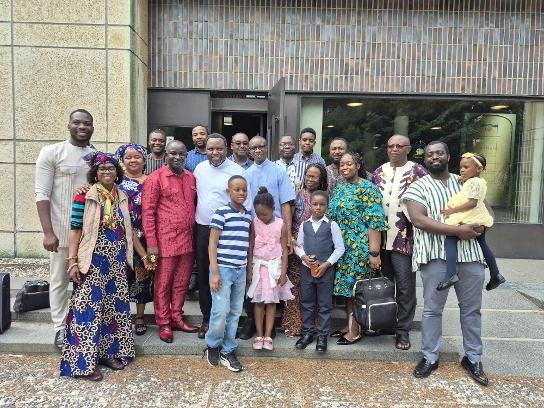
On special occasions, members of the Ghanaian Catholic community, in their gay and colourful kente attire and with adowa dance and music, usually lead the procession into the church. Other communities such as the Cameroonian, Nigerian, Kenyan and Tanzanian as well as Sudanese/South Sudanese groups also put up well-choreographed performances from their cultures.
The African Catholic Chaplaincy in Finland
The African Chaplaincy was founded on June 4, 2017, which was a Pentecost Sunday, in a Pontifical High Mass celebrated by Monsignor Emeritus Sippo S.C.I., the then Bishop of Helsinki, at the St. Mary’s Catholic Parish Church in Helsinki.
The Chaplaincy was created by Bishop Teemu in collaboration with the Diocesan body when they detected a great flocking of African immigrants to Finland, the majority of whom were Catholics. This was to give the immigrants a possibility to integrate into the Finnish society by worshiping as Catholics and in their African cultural identity.
The responsibility of the Chaplaincy was given by Bishop Teemu to Father Dr Leonard Wobilla Shwei, who is thus the first Chaplain and ably led the Chaplaincy. He was succeeded a few years ago by Father Thomas Otieno, who continues to move the Chaplaincy forward. Thank you!
GHANA MATTERS column appears fortnightly. Written in simple, layman’s terms, it concentrates on matters about Ghana and beyond. It focuses on everyday life issues relating to the social, cultural, economic, religious, political, health, sports, youth, gender, etc. It strives to remind us all that Ghana comes first. The column also takes a candid look at the meanings and repercussions of our actions, especially those things we take for granted or even ignore. There are key Ghanaian values we should uphold rather than disregard with impunity. We should not overlook the obvious. We need to search for the hidden or deeply embedded values and try to project them.
With Dr Perpetual Crentsil
SKIP THE QUEUE, TAP THE NEWS
You can now read the Ghanaian Times and The Spectator newspapers from the comfort of your device via TimesNewsPlus.
Join our WhatsApp Channel: https://whatsapp.com/channel/0029VbBElzjInlqHhl1aTU27
She did not find out he was cheating. She found out he was drowning.
It was two weeks after their beautiful wedding. The jollof was still in the fridge. A loan officer called her number-not his-and politely asked, “Madam, please tell your husband to pay his overdue loan. We have been calling him.”
That was how she discovered her new husband had entered their marriage with a hidden debt of over GH¢ 40,000. No cheating. No other woman. Just a financial secret.
And that is how many Ghanaian marriages begin to die. Not with a shout, but with a secret alert on a phone.
We prepare for the wedding. We do not prepare for the wallet.
What is money honesty?
Let me define it simply. Money honesty is not that you both earn the same. It is that you both know the same. It is the ability to sit down and say without fear:
“This is how much I earn.”
“This is how much I owe.”
“This is how I was raised to see money.”
“This is what scares me about money.”
Financial transparency is not about control. It is about clarity. You cannot build trust on top of secrets.
Many couples tell me, “Counsellor, we love each other, love will handle money.” I always answer, “Love is the car, but money honesty is the fuel. Love without honesty cannot move.”
How To Buy Your Marriage Insurance Today – My 5-Step Protocol
If you are engaged, newly married, or even 20 years in marriage, you can still fix this. At Counsellor Prince & Associates Consult—CPAC, this is what I give couples:
Step 1: The 90-Minute Money Naked Session.
No phones, no blame. Each partner writes down on paper: Monthly income, monthly debts, monthly family obligations, savings, and your biggest money fear. Then you exchange papers. Read it. Don’t react for 24 hours. Just absorb.
Step 2: Create OUR Money, YOUR Money, My Money.
You need three pots. OUR money for rent, food, school fees, utilities, properties, and the like— joint contribution. YOUR money and MY money—a small agreed allowance no one questions. This stops the feeling of being controlled.
Step 3: The No-Secret Debt Rule.
Agree from today: No new loan, no new hire purchase, no new family financial commitment above GHS 500 without telling each other first. Not permission, but information.
Step 4: Talk About Your Money Personality.
Are you a Spender or a Saver? Are you Risky or Safe? Most Ghanaian marriages are a Spender married to a Saver. Neither is wrong. But if you don’t understand your partner’s personality, you will call his saving “stinginess” and her spending “wastefulness.”
Step 5: Do a Monthly 30-Minute Money Date
Not an argument date. Light, with tea. “How did we do this month? What worried you? What should we plan for next month?” Couples who do this divorce far less.
My Final Word
Before you say “I Do” at the altar, have pre-marital counselling and also have the money talk on the sofa.
Ask your partner:
“If I lost my job today, how long can we survive?”
“What debt are you bringing into this marriage?”
“How much do you send to your family monthly and will that continue?”
If he or she gets angry that you asked, don’t get married yet. A person who is angry about accountability will be abusive about money.
Marriage insurance is not bought at Star Assurance or Enterprise. It is bought in honest conversations when no one is watching.
The wedding costs one day. The marriage costs a lifetime. Don’t enter a lifetime contract and covenant with hidden costs.
You can still insure your marriage today.
Source:
Counselor Prince Offei, CPAC’s founder, is a leading Mental Health Professional, Marriage Counsellor, Author, ADR Expert/Arbitrator, and Spectator Newspaper Columnist. He writes on relationships, marriage, parenting, special needs support, and their connection to mental health. For therapy, counselling, or enquiries, contact Counselor Prince & Associates Consult (CPAC) in Accra on 0559850604 / 0551428486.
SKIP THE QUEUE, TAP THE NEWS
You can now read the Ghanaian Times and The Spectator newspapers from the comfort of your device via TimesNewsPlus.
Join our WhatsApp Channel: https://whatsapp.com/channel/0029VbBElzjInlqHhl1aTU27